

By Richard Shumba The cost of digital fraud is not always measured by the amount of money lost. For victims, an incident can leave behind anxiety, mistrust and a constant fear of making financial transactions online, long after the money has disappeared. When Hope Ncube lost US$100 after being deceived by someone impersonating her work
By Richard Shumba
The cost of digital fraud is not always measured by the amount of money lost. For victims, an incident can leave behind anxiety, mistrust and a constant fear of making financial transactions online, long after the money has disappeared.
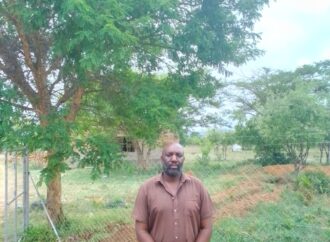
When Hope Ncube lost US$100 after being deceived by someone impersonating her work colleague, she expected that reporting the incident would help her recover the money.
But when The Sun Newspapers revisited Ncube to establish how she had been coping following the loss and what steps she had taken to protect herself, she revealed that she had since given up pursuing the case.
Ncube said she had repeatedly been told that the matter was still under investigation but had not received a conclusive outcome, prompting her to abandon efforts to pursue the case.
She said she had not recovered the money and that the police had told her investigations were still ongoing. According to Ncube, officers explained that investigations take time in every case and that the perpetrators could be apprehended either today or tomorrow, adding that the full wrath of the law would take its course. However, she said the police had indicated that they were still unable to trace the EcoCash number used in the transaction.
Although she has since recovered mentally and emotionally from the incident, the experience has left her apprehensive about online activities.
She said she had, however, become more conscious of digital security risks and taken a decisive approach towards protecting her money.
Following recommendations from her bank, First Capital Bank, and mobile money operator EcoCash, Ncube said she had changed her PIN and incorporated the security measures recommended by the two institutions into her financial activities.
The incident also prompted her friend to consult an IT professional, who inspected her devices to establish whether they had been hacked. Ncube also said her friend alerted work colleagues through a workplace WhatsApp group about the incident to warn others and raise awareness of the scam.
Speaking to this publication Econet wirelss customer services department who identified herself only as Gamuchirai said that Econet has since been
advising it’s subscribers to stay vigilant and alert.
” The public must note that Econet Wireless Zimbabwe makes its communication and adverts via their official pages and is not affiliated with any promotional adverts that come via links and on random pages. We however advise that the public not disclose any personal details to such adverts since most internet fraudsters use such baits to lure people into giving out confidential details which leave their EcoCash PIN and bank details vulnerable to attacks, ” she said .
She also encouraged WhatsApp users to activate passkeys and two-step verification, avoid sharing verification codes and regularly check devices linked to their accounts.
Ncube’s experience illustrates how digital fraud can affect not only people’s finances but also their confidence in using online services.
While she has taken steps to protect herself, her concerns reflect a wider challenge confronting Zimbabwe’s growing digital financial services sector.
Police warn of growing digital fraud tactics
The concerns raised by Ncube reflect wider challenges facing digital financial services users, with police warning that criminals are exploiting gaps in digital literacy and cybersecurity awareness to target unsuspecting members of the public.
In an interview with this publication Midlands Provincial Community Relations Liaison Officer Inspector E. Mahoko said opportunistic criminals were taking advantage of the convenience brought by digital financial integration to perpetrate different forms of online and banking fraud.
“While digital financial integration has brought convenience to the public, opportunistic criminals have been observed to be exploiting gaps in digital literacy and cyber safety,” Mahoko said.
He identified phishing and smishing scams, card cloning, unauthorised account access, advance-fee scams, fraudulent online shopping and identity theft among the methods being used by criminals.
Mahoko said some victims were lured through fraudulent SMS messages and WhatsApp links requesting them to update their banking or mobile money credentials, while others lost money after making advance payments for goods advertised on social media.
He also warned about criminals impersonating banking officials and public figures to obtain sensitive information, including one-time passwords (OTPs) and PINs.
On the police response, Mahoko said the Zimbabwe Republic Police (ZRP) had instituted investigations through its Criminal Investigations Department (CID) Commercial Crimes Division and Cybercrime Unit to trace electronic money transactions, identify compromised accounts and track suspected criminal syndicates.
He said the police were also working with financial institutions, mobile network operators and statutory bodies such as the Postal and Telecommunications Regulatory Authority of Zimbabwe (POTRAZ) to facilitate account freezing, digital evidence collection and the tracking of suspects.
“Inter-agency collaboration is essential in expediting account freezing, digital evidence collection and suspect tracking,” he said.
Mahoko urged financial institutions, the media and members of the public to work closely with the police in combating online and banking fraud.
He cautioned the public against sharing confidential banking information, emphasising that legitimate banking officials and police officers would not request customers’ card PINs, online banking passwords or OTPs over the phone.
He also urged people buying goods online to verify sellers before transferring money, particularly in peer-to-peer transactions involving vehicles, livestock and agricultural inputs.
Mahoko said victims should immediately report suspicious transactions to their financial service providers to facilitate possible account freezes before lodging formal reports at their nearest police stations, accompanied by relevant transaction references.
He further advised members of the public to avoid clicking on unverified links received through SMS, email and social media platforms.
RBZ must take leading role in protecting consumers
While police investigations and public awareness remain important in addressing digital financial fraud, questions remain about the responsibilities of regulators and financial service providers when consumers lose money or encounter problems with electronic transactions.
Meanwhile, Lecturer in the Department of Information Systems at Midlands State University, Samuel Musungwini says the Reserve Bank of Zimbabwe (RBZ) should take a leading role in ensuring that the country’s digital payment ecosystem is secure, accessible and competitive.
Musungwini argues that the central bank should act as the principal steward of the national payments ecosystem by enforcing payment-system rules, establishing transparent participation criteria and supervising settlement risks.
“The RBZ should act as the principal steward of an open, secure and competitive national payments ecosystem,” he said.
He said the central bank should also monitor transaction charges and require financial service providers to maintain consistent standards for cybersecurity and consumer protection.
Musungwini further recommends coordination between the RBZ and POTRAZ on communications infrastructure, as well as competition authorities to address discriminatory access and market abuse.
Zimbabwe already has a regulatory framework governing payment systems through the National Payment Systems Act [Chapter 24:23] and Statutory Instrument 80 of 2020.
Musungwini also identifies the RBZ’s FinTech Regulatory Sandbox Guidelines as an important instrument for encouraging innovation under regulatory supervision.
However, he maintains that innovation should not undermine consumer protection.
He argues that collaboration between financial service providers should be compulsory where public interest requires it, while competition should be maintained in customer-facing services.
What happens when a transaction fails?
Beyond suspected fraud, Musungwini says consumers also need clear procedures for dealing with failed transactions, delayed payments and transfers made to unintended recipients.
He argues that financial service providers should distinguish between these circumstances because each requires a different response.
“A failed transaction should not leave customers indefinitely without either their funds or confirmation of successful payment,” he said.
According to Musungwini, providers should investigate failed transactions promptly, prevent duplicate debits and reverse unsuccessful payments where appropriate.
For delayed transfers, he says customers should receive accurate updates on transaction status and be provided with traceable payment references.
He also notes that accidental transfers to the wrong recipient require prompt recovery efforts, although providers should not debit another person’s account without lawful authority.
Of particular concern, he says, are payments made after customers have been deceived through impersonation or other forms of social engineering.
“Similarly, a payment induced by impersonation requires fraud investigation rather than an assumption that every successfully authenticated transaction is beyond challenge,” Musungwini said.
He argues that the RBZ should prescribe measurable service standards covering transaction acknowledgement, investigations, reversals where warranted, escalation procedures and written decisions.
“The customer should never have to determine which institution caused a failure before receiving assistance,” he said.
Research highlights importance of consumer trust
Musungwini’s recommendations are informed by his academic work on consumer confidence and the adoption of digital financial services.
In a study co-authored with Theo Tsokota and Amanda Mutembedza, titled A Strategy to Enhance Consumer Trust in the Adoption of Mobile Banking Applications, the researchers examined factors influencing the uptake of mobile banking applications in Zimbabwe.
Published in the African Journal of Science, Technology, Innovation and Development in 2022, the research focused on CBZ Touch, examining security, trust and other factors affecting consumers’ adoption of mobile banking.
The researchers used questionnaires and interviews involving CBZ Touch users to assess their experiences and perceptions of mobile banking.
Their findings highlighted the importance of application quality, usefulness, cost and social influence, while recommending that financial institutions regularly communicate security threats and available protection mechanisms.
The researchers argued that improving the quality of mobile banking applications and keeping customers informed about security risks could strengthen consumer confidence and encourage adoption.
For Zimbabwe, the findings raise an important consideration as digital financial services continue to expand: access to electronic payments must be accompanied by effective safeguards and reliable mechanisms for resolving disputes.
For Ncube, changing her PIN and becoming more cautious online are steps towards rebuilding her confidence.
But her decision to abandon the recovery process after receiving repeated assurances that investigations were underway leaves a wider question about the support available to consumers who lose money through digital payment fraud.
As the country moves towards greater digital financial inclusion, the challenge for regulators and financial service providers is not simply to make transactions faster, but to ensure that consumers have confidence in the systems they increasingly depend on.






Leave a Comment
Your email address will not be published. Required fields are marked with *